Tag: business

  • Step-by-Step Junk Car Sale in Coconut Creek

    Step-by-Step Junk Car Sale in Coconut Creek

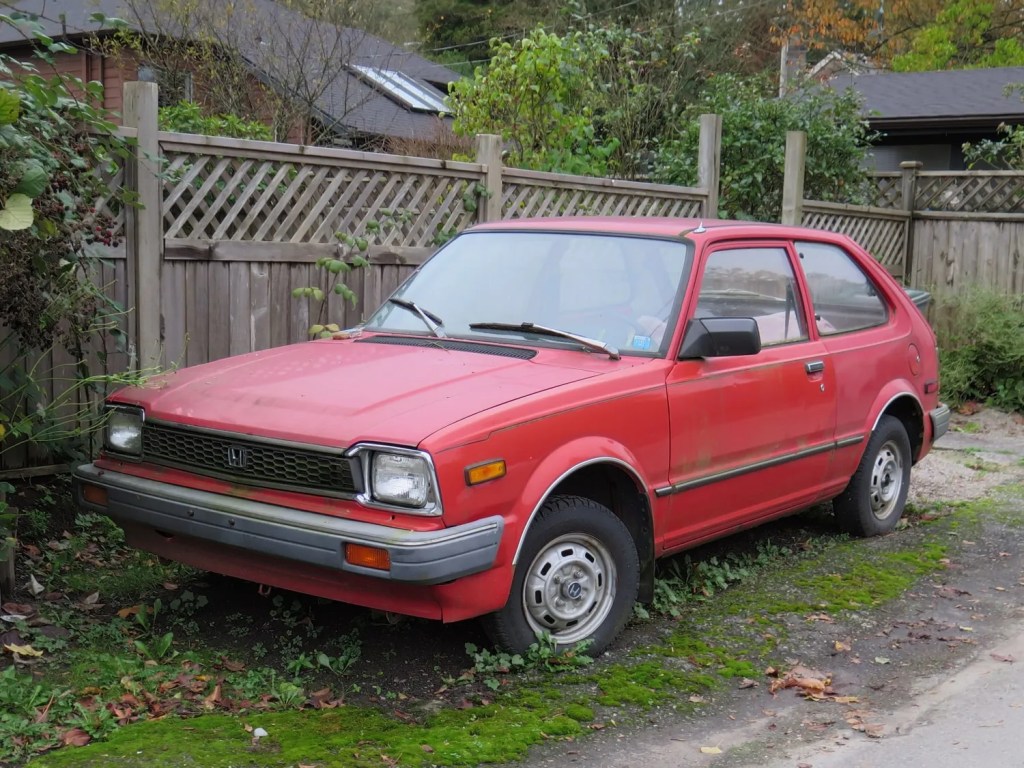
    So you’ve got a junk car sitting in your driveway. Maybe it hasn’t started in months. Maybe the repair costs are more than the car is worth. Or maybe you’re just tired of looking at it every morning when you grab your coffee.

    Whatever the reason, selling a junk car in Coconut Creek doesn’t have to be a headache. In fact, once you know the steps, the whole process can be surprisingly smooth. Let me walk you through it from start to finish.

    First Things First: Decide If Your Car Is Really “Junk”

    Before you do anything else, take an honest look at your vehicle. A junk car doesn’t necessarily mean a car that’s completely destroyed. It could be a vehicle that costs more to fix than it’s worth. It could be one that failed inspection or has a blown engine. Even a car that runs but has major body damage can qualify.

    If you find yourself avoiding the mechanic because you already know the news will be bad, that’s a pretty good sign you’re dealing with a junk car.

    The good news? Even junk cars have value. The metal, parts, and components inside your vehicle are worth something to the right buyer. So don’t assume your old beater is worthless.

    Step 1: Gather Your Paperwork

    This is where a lot of people get tripped up, but it really doesn’t have to be complicated. The most important document you need is your car title. In Florida, the title proves you own the vehicle and have the legal right to sell it.

    If you’ve lost your title, don’t panic. You can apply for a duplicate through the Florida Department of Highway Safety and Motor Vehicles. It takes a little time, but it’s doable.

    You should also have your driver’s license or a valid ID handy. Some buyers might ask for the registration too, though that’s not always required.

    Having your paperwork ready before you start reaching out to buyers saves time and shows you’re serious about the sale.

    Step 2: Know What Your Car Is Worth

    You don’t need to be a mechanic or an appraiser to get a rough idea of your car’s value. Start by noting the basics. What’s the year, make, and model? What kind of condition is it in? Does it run? Are there major parts missing?

    These details matter because they affect how much a buyer will offer. A 2015 sedan with a bad transmission is going to fetch more than a 2003 minivan that’s been sitting in a field for three years.

    Do a little research online or call around to a few buyers in the Coconut Creek area to compare offers. This helps you avoid accepting a lowball price when your car could be worth more.

    Step 3: Choose the Right Buyer

    This step is crucial. Not all junk car buyers operate the same way. Some will give you a fair price and handle everything professionally. Others might hit you with hidden fees or change the price when they show up.

    Look for a buyer who offers free towing, gives you a quote upfront, and doesn’t charge extra for pickup. A reputable junk car buyer in Coconut Creek should make the process easy and transparent from the very first phone call.

    Ask questions. How do they determine the price? When can they pick up the car? Will they handle the paperwork? A trustworthy buyer won’t dodge these questions.

    Step 4: Get Your Quote

    Once you’ve found a buyer you feel comfortable with, it’s time to get an official quote. Most junk car buyers will ask you a few questions about the vehicle over the phone or online. Be honest about the condition. If there’s rust, body damage, or missing parts, say so.

    Giving accurate information upfront prevents awkward surprises later. Nobody wants to agree on a price only to have it change when the tow truck arrives.

    A good buyer will give you a firm offer and stick to it.

    Step 5: Schedule the Pickup

    Here’s where things get really easy. Once you accept the offer, the buyer will schedule a time to come pick up your car. In most cases, this can happen within a day or two. Some buyers even offer same-day pickup if the timing works out.

    Make sure the car is accessible. Clear out any personal belongings you might have left inside. Check the glove box, under the seats, and in the trunk. You’d be surprised how many people forget sunglasses, phone chargers, or important documents tucked away in their old cars.

    Step 6: Complete the Sale

    When the buyer arrives, they’ll inspect the car, finalize the paperwork, and pay you. Most reputable buyers pay cash on the spot. You sign over the title, they load up the car, and that’s it. Done.

    After the sale, make sure you notify the Florida DMV that you’ve sold the vehicle. This protects you from any liability issues down the road. It only takes a few minutes and gives you peace of mind.

    Why Coconut Creek Residents Shouldn’t Wait

    Junk cars don’t gain value sitting around. In fact, they lose value over time as parts rust and deteriorate. They can also attract fines from your HOA or local code enforcement. And let’s be real, they take up space you could be using for something better.

    Selling your junk car puts cash in your pocket and clears up your property. It’s one of those tasks that feels so much better once it’s actually done.

    The Bottom Line

    Selling a junk car in Coconut Creek is straightforward when you break it down into simple steps. Gather your paperwork, know your car’s value, find a reliable junk car buyer, get a fair quote, schedule the pickup, and complete the sale. That’s really all there is to it.

    Your old car served its purpose. Now it’s time to let it go and move on. And honestly, your driveway will thank you.
  • Beyond SBA Loans: Flexible Financing Options for Growing Businesses

    Beyond SBA Loans: Flexible Financing Options for Growing Businesses

    Growing businesses often reach a point where traditional financing no longer fits their immediate needs or timelines. While SBA loans remain a popular option, they can involve lengthy approval processes and strict qualification standards. Many business owners seek funding solutions that provide quicker access to capital and greater flexibility. Alternative financing options can help companies manage inventory purchases, payroll expenses, equipment upgrades, or expansion plans more efficiently.

    Different funding structures also allow businesses to choose repayment terms that better align with their cash flow patterns. Understanding the available options helps business owners make informed financial decisions without relying on a single lending source. Exploring various financing methods can create more opportunities for sustainable growth in competitive industries.

    Traditional Asset-Based and Cash-Flow-Based Loans

    Businesses that own valuable equipment, inventory, or accounts receivable may qualify for financing secured by those assets. Asset-based lending allows companies to borrow against existing business resources, which can provide access to larger amounts of capital compared to unsecured loans. Cash-flow-based loans, on the other hand, focus more heavily on the company’s revenue performance and future earnings potential.

    These financing methods are often considered practical SBA loan alternatives for businesses that may not meet traditional SBA lending requirements. Lenders typically evaluate financial stability, operational history, and repayment ability before approving funds. Companies experiencing rapid growth sometimes prefer these options because they can offer faster approvals and flexible borrowing structures. Choosing between asset-based and cash-flow-based financing depends largely on the company’s financial position and long-term goals.

    Business Lines of Credit for Ongoing Flexibility

    A business line of credit offers access to revolving funds that companies can use whenever needed. Unlike traditional lump-sum loans, businesses only pay interest on the amount they actually borrow. This financing option can help manage short-term operational costs, seasonal fluctuations, or unexpected expenses without disrupting daily operations. Many business owners appreciate the flexibility of drawing funds repeatedly as long as the account remains in good standing.

    Lines of credit can also support smoother cash flow management during periods of uneven revenue. Some lenders provide secured and unsecured options depending on the company’s financial profile and collateral availability. Having access to revolving capital can give businesses more confidence when planning for growth opportunities or handling temporary financial challenges.

    Equipment Financing for Expanding Operations

    Equipment financing helps businesses acquire machinery, vehicles, technology, or specialized tools without paying the full cost upfront. This type of funding is especially useful for industries that rely heavily on operational equipment to maintain productivity. The purchased equipment itself often serves as collateral, which may make approval easier for some businesses.

    Monthly payments are typically structured over a fixed term, allowing companies to spread costs over time while preserving working capital. Upgrading equipment can improve efficiency, reduce downtime, and support higher production capacity. Many businesses use equipment financing to stay competitive without significantly affecting their day-to-day cash reserves. Careful planning ensures that the investment contributes positively to long-term operational growth and profitability.

    Invoice Financing and Short-Term Funding Solutions

    Invoice financing allows businesses to access immediate cash by using unpaid customer invoices as collateral. This approach can help companies maintain healthy cash flow while waiting for clients to complete payments. Businesses that work with long payment cycles often benefit from quicker access to operating funds through invoice-based financing. Short-term funding solutions can also help cover payroll, supplier payments, or emergency operational expenses during slower periods.

    These financing methods are commonly used by businesses that experience temporary gaps between outgoing costs and incoming revenue. Approval processes for invoice financing are often faster because lenders focus heavily on customer payment reliability. When used responsibly, short-term financing can support stability and reduce financial pressure during periods of growth or transition.

    Final Thoughts

    Selecting the right financing strategy requires a clear understanding of business goals, financial health, and operational priorities. Each funding option comes with its own advantages, repayment structures, and qualification requirements. Business owners should carefully evaluate how financing will affect cash flow, profitability, and future expansion opportunities.

    Comparing lender terms, interest rates, and repayment flexibility can help companies avoid unnecessary financial strain. It is also important to consider whether the financing supports short-term needs or contributes to long-term strategic growth.

    Consulting financial professionals or experienced advisors may provide additional insight when evaluating multiple lending solutions. With thoughtful planning, businesses can secure funding that supports both stability and continued growth beyond traditional lending programs.

  • Smart Money Moves: Financial Must-Haves for Growing a Small Business

    Smart Money Moves: Financial Must-Haves for Growing a Small Business

    Growing a small business requires more than just offering a great product or delivering reliable services to customers. It depends heavily on making consistent and informed financial decisions that support both day-to-day operations and long-term goals. Without a clear financial strategy, even profitable businesses can face instability due to poor cash flow, unmanaged expenses, or limited planning.

    Business owners who take time to understand their finances are better equipped to handle uncertainty and adapt to market changes. Strong financial habits also make it easier to identify opportunities for expansion and investment. By focusing on core financial essentials, small businesses can build a solid foundation that supports sustainable growth over time.

    Business Financing and Loans

    Access to reliable financing is one of the most important resources for a growing small business. Many business owners use a combination of personal funds, retained earnings, and external funding to support their operations and expansion efforts. Having access to capital allows businesses to invest in equipment, hire employees, or increase inventory when demand rises. However, borrowing should always be approached with careful planning and a clear understanding of repayment obligations. Evaluating interest rates, repayment terms, and eligibility requirements helps ensure that financing aligns with the business’s financial capacity.

    In some cases, small business loan providers such as Advantage Capital offer structured financing options, including traditional asset-based and cash-flow-based loans, often with competitive interest rates and reduced or no closing fees. Selecting the right type of financing helps provide flexibility while keeping financial pressure manageable. When used responsibly, small business loans can serve as a strategic resource that supports growth and opportunity rather than becoming a long-term financial burden.

    Budgeting and Cash Flow Management

    Budgeting is a fundamental practice that allows small business owners to plan how money is spent and allocated across different areas of the business. A well-prepared budget helps ensure that resources are used efficiently and aligned with business priorities. Cash flow management, on the other hand, focuses on tracking the movement of money in and out of the business on a regular basis.

    Maintaining positive cash flow is essential because it ensures that the business can meet its financial obligations without delays. Regular monitoring of expenses and income helps identify patterns that may affect profitability. Many businesses benefit from using accounting tools or software to simplify tracking and improve accuracy. Consistent budgeting and cash flow oversight enable owners to make informed decisions and avoid unexpected financial challenges.

    Wealth Management

    Wealth management is an important consideration for small business owners who want to balance business growth with personal financial security. It involves organizing assets, planning investments, and developing strategies to preserve and grow wealth over time. As a business becomes more profitable, owners often face decisions about how much to reinvest versus how much to allocate toward personal financial goals. Establishing a clear financial plan can help maintain this balance while supporting long-term stability.

    Many financial planning resources such as Presidio Wealth Management help guide broader financial strategies, including handling and allocating assets alongside business operations in a structured and balanced way. Diversifying investments can help reduce risk and protect against market fluctuations. Regular financial reviews allow business owners to adjust their strategies as their business evolves and their financial situation changes.

    Risk Management and Emergency Funds

    Risk management is essential for preparing a small business to handle unexpected events that may disrupt operations. These risks can include economic downturns, supply chain disruptions, or sudden changes in customer demand. One of the most effective ways to manage risk is by maintaining an emergency fund that can cover essential expenses during difficult periods.

    Having financial reserves provides a cushion that allows the business to continue operating even when revenue temporarily declines. Insurance coverage is another key component, as it helps protect against losses related to property damage, liability, or other unforeseen incidents. Regularly reviewing potential risks helps business owners stay proactive rather than reactive. By combining preparation, financial reserves, and protection strategies, businesses can improve their resilience and stability.

    Accounting and Financial Tracking

    Accurate accounting practices are vital for maintaining a clear picture of a business’s financial health. Keeping detailed records of all transactions ensures that income and expenses are properly documented and organized. Financial statements such as profit and loss reports and balance sheets provide insights into performance and overall stability. These reports help business owners identify trends, monitor profitability, and make informed decisions about future investments.

    Using accounting software or working with professionals can improve accuracy and reduce the likelihood of errors. Consistent financial tracking also simplifies tax preparation and ensures compliance with regulatory requirements. Over time, strong accounting practices contribute to better planning, improved transparency, and more confident decision-making.

    Conclusion

    Financial management plays a central role in the success and growth of any small business. By focusing on key areas such as financing, budgeting, wealth planning, risk management, and accounting, business owners can create a well-rounded approach to handling their finances. Each of these elements supports better decision-making and helps reduce uncertainty in daily operations.

     When financial systems are organized and consistently maintained, businesses are more likely to remain stable during challenges and capitalize on opportunities for expansion. Developing strong financial habits early can also prevent common issues that many growing businesses face. Ultimately, a thoughtful and disciplined approach to financial management allows small businesses to grow with confidence and long-term sustainability.

Create your own website, free on WordPress.com.Create your own website.
Start free